Complete Guide to Power of Attorney for Aging Parents
Everything you need to know about POA types, when to get one, the process for obtaining it, and how to use it responsibly.
Read Guide
Managing your parents' finances and legal affairs can feel overwhelming. From power of attorney to Medicare enrollment, we'll help you understand what you need to know and when.
The short version: to manage an aging parent's finances, first secure legal authority (a durable power of attorney and a healthcare proxy), then map every income source, account and policy, then automate and protect the money, and only then plan and price long-term care. The four-stage checklist below puts those steps in order, with a guide for each.
Updated 2026. General information, not legal, tax or financial advice. Laws vary by state; consult an elder law attorney or tax professional for your situation. See our disclaimer.
| Task | Why it matters | Guide |
|---|---|---|
| ☐ Confirm who has legal authority | Without a durable power of attorney, banks will not talk to you, and getting guardianship later is slow and expensive. | Power of attorney guide |
| ☐ Sign a healthcare proxy and HIPAA release | Lets you speak with doctors and make medical decisions if your parent cannot. | Healthcare proxy guide |
| ☐ Locate the core documents | Will or trust, deeds, vehicle titles, insurance policies, tax returns, Social Security and Medicare cards, military discharge papers. | Documents checklist |
| ☐ List every income source | Social Security, pensions, annuities, retirement withdrawals, rental income. This sets the monthly baseline for every later decision. | Social Security strategies |
| ☐ Write down every account and debt | Bank, brokerage, retirement, credit cards, mortgage, loans, safe deposit box, online logins. One page, stored securely. | Financial organization guide |
| Task | Why it matters | Guide |
|---|---|---|
| ☐ Set up bill pay and mail routing | Autopay for fixed bills and a monthly review prevent missed payments, which are an early sign of cognitive decline. | Managing parents money |
| ☐ Put a credit freeze on all three bureaus | Free at Equifax, Experian and TransUnion, and the simplest protection against new-account fraud. | Financial abuse guide |
| ☐ Review beneficiary designations | Beneficiaries on retirement accounts and life insurance override the will, and out-of-date ones cause family fights. | Beneficiary guide |
| ☐ Check Medicare, Medigap and Part D | Confirm what is covered, premiums, and whether the plan still fits current prescriptions. Review again every fall during the annual enrollment period. | Medicare enrollment |
| ☐ Screen for benefits | Medicare Savings Programs, Medicaid, SNAP, energy assistance and VA benefits go unclaimed by millions of eligible seniors. | Benefits checker |
| Task | Why it matters | Guide |
|---|---|---|
| ☐ Price out the care you may need | Compare home care, assisted living, memory care and nursing home costs for your parent's ZIP code. | Assisted living cost by ZIP |
| ☐ Review long-term care insurance | Find out whether a policy exists, what triggers benefits and what the elimination period is. | Long-term care insurance |
| ☐ See an elder law attorney before moving assets | Medicaid reviews asset transfers from the prior five years, so gifting or retitling can cost eligibility. | Asset protection |
| ☐ Update the will, trust and funeral wishes | A will, living will and a funeral or final expense plan spare the family decisions in a crisis. | Estate planning basics |
| Task | Why it matters | Guide |
|---|---|---|
| ☐ Plan for taxes | Keep receipts: unreimbursed medical costs above 7.5 percent of adjusted gross income can be deducted if you itemize, and a parent may qualify as a dependent. | Tax planning for caregivers |
| ☐ Watch for fraud and exploitation | Review statements monthly, set bank alerts, and know the warning signs of scams and undue influence. | Financial abuse guide |
| ☐ Keep sibling and family records | A shared log of money spent on your parent's behalf prevents disputes and supports any caregiver agreement. | Get paid to care for parents |
| ☐ Re-review every year | Beneficiaries, insurance, accounts, authority documents and the care budget all drift. Put a yearly date on the calendar. |
Work top to bottom, and do not let the later stages wait on perfect paperwork. If your parent still has capacity, the authority documents come first, because a power of attorney can only be signed by someone who understands what they are signing. If there is already a crisis, such as a fall or a hospital stay, start with Stage 1 and the emergency contact card, then come back to the rest.
Keep everything in one place. A paper binder or secure shared folder that lists accounts, contacts and where documents live is the difference between a calm handover and a scramble. The book below is built for exactly that.
Legal authority documents, a list of income, accounts, debts and insurance policies, bill pay and fraud protection, beneficiary reviews, benefit screening, a long-term care cost plan, tax records and a yearly review.
A durable power of attorney is the key one for finances, plus a healthcare proxy and HIPAA release for medical matters. Banks often want their own power of attorney form or will review yours, so ask each institution what it accepts.
Start the conversation and the documents before there is a problem. Signs it is time to step in include unpaid bills, unexplained withdrawals, new unfamiliar accounts, confusion about money, or a new diagnosis affecting memory.
Generally not, except as a named joint owner or authorized signer. Without authority, you may need a conservatorship or guardianship through the court, which is slower and costly, so sign a power of attorney while your parent still has capacity.
Use the tables above as your list, and print our essential documents checklist alongside it. The Complete Caregiver Toolkit adds fill-in versions of these worksheets.
The companion book
by Riley Bennett
A fill-in caregiver organizer for medical, legal, financial, insurance and daily-care information, with an emergency plan and appointment log. Worksheets for contacts, medications, insurance numbers, legal documents, home safety and a one-page emergency sheet, in one paperback you keep where the care happens.
Paperback on Amazon →Financial and legal planning for aging parents involves some of the most important, and often most uncomfortable, conversations you'll have as a family. Yet proper planning now can prevent crises later, protect your parents' assets, ensure their wishes are honored, and give everyone peace of mind. These guides walk you through each step, explaining complex topics in plain language.
We cover the essential legal documents every family needs: power of attorney, healthcare proxies, wills, and trusts. You'll learn how Medicare, Medicaid, and supplemental insurance work together, and how to maximize benefits while minimizing out-of-pocket costs. For families facing long-term care decisions, we explain asset protection strategies, veterans benefits, and how to navigate the complex world of care financing.
Whether your parents are healthy and planning ahead, or you're facing an immediate need to take over their financial affairs, these resources will help you understand your options and take confident action. We always recommend consulting with qualified attorneys and financial advisors for your specific situation, these guides help you know what questions to ask.
Everything you need to know about POA types, when to get one, the process for obtaining it, and how to use it responsibly.
Read GuideA step-by-step guide to taking over bill paying, organizing accounts, and managing your parents' money responsibly.
Read GuideMost of what caregiving costs is time. These four are the purchases that reliably buy some of it back, and they are the ones families tell us they wish they had bought sooner.
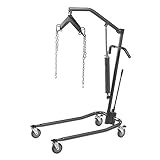 Drive Medical Hydraulic Patient Lift
A full lift is what makes one person able to manage a transfer alone. It is the single purchase that most often delays a move into residential care.
Check price on Amazon →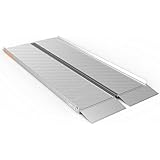 EZ-ACCESS Singlefold Wheelchair Ramp, 6 ft
Folds like a suitcase and carries in a car boot, so the same ramp handles the front step at home and the kerb at an appointment.
Check price on Amazon → Drive Medical Nitro Rollator with Seat
The seat matters more than the wheels. Being able to stop and rest is what decides whether someone still goes out at all.
Check price on Amazon → Vive Stand Assist Rail for Couch or Chair
Getting out of a low sofa is where most falls at home start. This is the cheapest thing on the list and often the first one needed.
Check price on Amazon →As an Amazon Associate we earn from qualifying purchases, at no extra cost to you. Researched guidance, not medical advice. Prices change, so check before buying.
Essential legal tools for protecting your parents and making decisions on their behalf.
Complete printable checklist of legal, medical, financial, and insurance documents you need.
Get checklist →Legal authority to make financial decisions for your parent when they can't.
Learn more →When POA isn't enough: court-appointed authority for incapacitated parents.
Learn more →Get access to your parent's medical records and speak with their doctors.
Learn more →Manage Social Security benefits for a parent who can't handle their own finances.
Learn more →Day-to-day financial management and organization.
Medicaid, VA programs, and other ways family caregivers can receive compensation.
Learn more →Set up systems for paying bills, managing accounts, and preventing missed payments.
Learn more →Create a complete inventory of accounts, assets, debts, and important documents.
Learn more →Tax considerations for caregivers and strategies to reduce your parents' tax burden.
Learn more →When to claim, spousal benefits, and maximizing lifetime benefits.
Learn more →Understanding healthcare coverage options for seniors.
When to enroll, how to avoid penalties, and special enrollment periods.
Learn more →Understand the differences, eligibility, and how they can work together.
Learn more →Preparing for the future and protecting your parents' legacy.
Keeping retirement accounts, insurance, and bank accounts properly designated.
Learn more →Protecting assets from Medicaid spend-down and long-term care costs.
Learn more →Planning for aging parents of adult children with disabilities.
Learn more →Our Power of Attorney guide walks you through the most important first step in managing your parents' affairs.
Read the POA GuideConnect with 53 million caregivers actively researching solutions for their aging parents.
New to the terms? The elder care and senior living glossary defines ADLs, POA, spend-down, CCRC and the rest in plain English.
Keep exploring with these hand-picked guides on related topics.
Which life insurance types accept older applicants, what it costs by age, and how to get a free quote for an aging parent.
What final expense insurance covers, what it costs, and how to decide if it is right for your aging parent.
Comprehensive guide to protecting your aging parent
Keep retirement accounts, life insurance, and bank accounts properly designated. Learn why beneficiary designations over
Complete checklist of documents you need for aging parents: legal, medical, financial, and insurance. Downloadable PDF c
Complete guide to estate planning for elderly parents. Learn about wills, trusts, power of attorney, healthcare directiv